
Central bank lowers inflation forecast to boost outlook for South African Economy
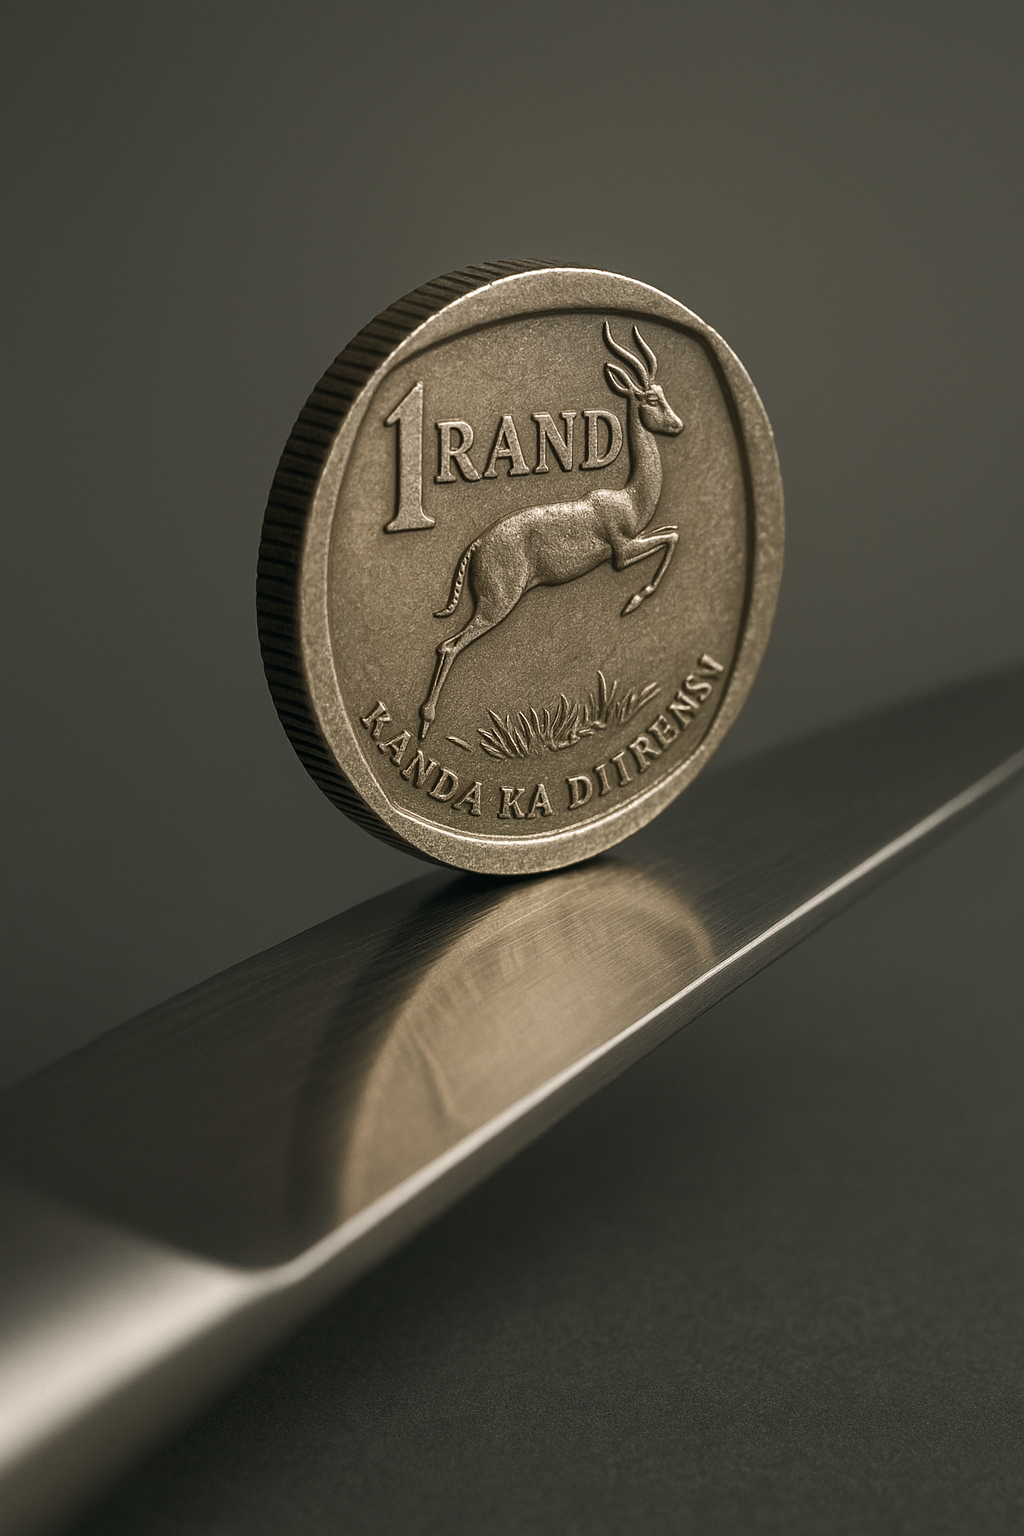
SARB cuts inflation forecast, signaling potential relief for South African households and businesses amidst a complex economic landscape.
A small 0.3% cut in South Africa's inflation guess is making big waves. Poorer homes get cheaper food, while others might pay less on loans. Big companies like Eskom could earn more, and mines might save on worker pay. Markets are excited, hoping for interest rate cuts, which brings in money and boosts stocks. But everyone knows this good news could easily change if things like power cuts or currency problems pop up again.
How does a 0.3% cut in South Africa's CPI forecast impact households, corporations, and markets?
A 0.3% cut in South Africa's CPI forecast offers varied impacts. Households, particularly the poorest, benefit from cheaper food, while middle-income earners could see reduced debt service costs. Corporations like Eskom might gain a revenue windfall, and mining houses could save on wage demands. Financial markets anticipate potential interest rate cuts, leading to inflows and boosted equities, though long-term skepticism remains.
Get Cape Town news in your inbox
Stay updated with the latest stories from the Mother City.
1. The Forecast Whisper That Echoes from Taxi Ranks to Bond Desks
South Africa’s price pulse has forever balanced between imported diesel tremors and home-grown potholes that shove maize meal higher even when Chicago futures nap. Trimming the headline CPI outlook by 0.3 % may sound nerdy, yet the whisper races from Pretoria’s MPC chamber to a Durban taxi rank where a queue marshal reruns his July surcharge maths, to a Cape Town fixed-income trader juggling R186 duration.
That decimal-point edit is social media for the economy: it signals that the lethal trio of Eskom tariffs, Brent swings and rand tantrums might behave better than feared. But the promise holds only if the Free State really harvests 16 million tonnes, strike ballots stay boring, and the currency keeps its tantrums below the psychological R19.50 cliff.
Roughly three-fifths of the consumer basket is still cooked in political pots - electricity tariffs inked by Nersa, fuel formulas blessed by the DMRE, rates demands posted by 257 municipalities gasping for cash. The Reserve Bank only steers the thin but spicy slice of demand that feeds off the repo rate. When its models predict cooler price soup, they are betting that administered chilli will scald less than before - a wager the rest of us then price into taxi fares, grocery promotions and bond convexity.
2. Rand, Real Yields and the Global Dollar Dance
Foreign funds still sit on just under 30 % of government debt, down from 43 % five years ago, yet their fingerprints smudge the short end of the curve - especially the R2030 and its cousins - because local pension funds prefer the long belly. Global investors never eye nominal yield alone; they watch local real yield minus U.S. TIPS. A 0.3 % drop in expected CPI automatically widens that gap by the same amount unless nominal bond yields fall in tandem.
History says a 20-basis-point widening, if the U.S. MOVE volatility index behaves below 110, pulls R10–12 billion of inflows inside a fortnight. But let the one-year dollar-rand cross-currency basis swap balloon past −50 bp - signalling a global scramble for greenbacks - and the same carry hunters evaporate. In plain language: rand strength on disinflation news is a conditional gift that can be clawed back by a twitch in New York funding markets.
Currency options tell the same two-tier story. After the forecast tweak, the one-month risk-reversal skew flipped to favour the rand for the first time since May 2021, yet anything beyond six months remains stubbornly dollar-call-biased. Dealers read that as polite applause for the SARB’s credibility, not a standing ovation for the country’s structural story.
3. Households: From the Food Basket to the Mortgage Button
Stats SA’s Living Conditions Survey spells out the asymmetry. The poorest fifth of society devote 34 cents of every rand to food and non-alcoholic drinks, twice the share of the richest fifth. A CPI drop from 6 % to 4 % gifts them about R120 per month on a R3,000 budget - just enough to swallow the routine July spike in municipal tariffs without borrowing from the mashonisa.
Climb one rung to the middle quintile and the bigger headache is debt service, not bread prices. Roughly 18 % of their outgoings cover mortgages or vehicle paper. A quarter-point repo reduction, fully passed on, cuts the monthly payment on a R1 million, 20-year bond by R166. Probability of that cut rose from 25 % to 40 % in forward-rate agreement pricing once the inflation forecast moved south - call option value for the average suburban balance sheet.
Rural consumers, surveyed by the University of Cape Town’s Behavioural Economics Unit, recorded a nine-point jump in confidence, the sharpest since the 2020 reopening bounce. Yet intent to buy durable goods barely budged, proving that cheaper tomatoes are welcome but cannot replace a stagnant wage or an inaccessible loan.
4. Boardrooms, Basel IV and the Bond Market’s Front-Loaded Fairy Tale
For Eskom, lower inflation is a mixed blessing. April’s 18.65 % tariff jump was calculated on a 5 % CPI assumption. If prices instead rise 4.2 %, the utility pockets a real revenue windfall, buying breathing space on its debt pile while municipalities still collect the unpopular hike from residents.
Mining houses see the opposite relief. The Minerals Council reckons every percentage point shaved from inflation expectations trims central-bargaining wage demands by 0.6 %. Over a year, that saves a mid-sized platinum outfit with 20,000 employees about R1.1 billion - cash that can be diverted to solar rooftops instead of above-inflation pay packets.
Commercial banks, constrained by Basel IV risk-weighted asset creep, have kept credit growth at a lethargic 4 %. A credible disinflation path sweetens corporate debt-service-coverage ratios, enticing lenders to release general provisions. SARB studies show credit growth accelerating 1.3 % for every 1 % drop in expected inflation within four quarters - rocket fuel for an economy that has been running on fumes.
Bond traders reacted asymmetrically: the 10-year benchmark yield plunged 28 basis points, yet five-year-forward break-evens gave up only 9 bp, exposing scepticism that the good news survives beyond 2029. Domestic equity investors were less coy, shovelling R4.3 billion into rate-sensitive banks, retailers and property counters; the banks index surged 11 %, pricing in not just one cut but the entire narrative loop of lower defaults, cheaper goods and busier tills.
Whether that fairy tale materialises depends on variables the SARB can only pray for: winter load-shedding staying below 150 hours at stage-4, maize silos brimming, and Jerome Powell keeping his hawk on a leash. The forecast reset is therefore less a terminus than a new jumping-off point for taxi drivers, fund managers and finance ministers alike - each recalculating, re-pricing and holding their breath for the next data dump.
[{"question": "How does a 0.3% cut in South Africa's CPI forecast impact households, corporations, and markets?", "answer": "A 0.3% cut in South Africa's Consumer Price Index (CPI) forecast has a multifaceted impact. For households, especially the poorest, it means cheaper food, potentially saving them around R120 per month on a R3,000 budget if inflation drops from 6% to 4%. Middle-income earners could see reduced debt service costs due to a potential repo rate cut, saving about R166 monthly on a R1 million, 20-year bond with a quarter-point reduction. Corporations like Eskom might experience a real revenue windfall if tariffs were based on a higher CPI assumption. Mining houses could save significantly on wage demands, potentially diverting funds to other investments. Financial markets anticipate interest rate cuts, leading to inflows and boosted equities, particularly in rate-sensitive sectors like banking and retail."},
{"question": "What are the main factors influencing South Africa's inflation, and how conditional is the current positive outlook?", "answer": "South Africa's inflation is heavily influenced by a combination of imported factors like diesel prices and domestic issues such as electricity tariffs, fuel formulas, and municipal rates. Roughly three-fifths of the consumer basket is affected by politically determined prices. The current positive outlook, signaled by the 0.3% CPI forecast cut, is highly conditional. It hinges on factors such as a strong agricultural harvest (e.g., 16 million tonnes from the Free State), stable labor relations with minimal strikes, and the Rand maintaining its value, ideally staying below the R19.50 per dollar mark. Any resurgence in power cuts or currency instability could quickly reverse this optimistic forecast."},
{"question": "How do global financial movements, particularly the US dollar, affect the rand and South African bond markets?", "answer": "Global financial movements, especially the strength of the US dollar, significantly influence the rand and South African bond markets. Foreign funds hold a substantial portion of government debt, and their investment decisions are driven by real yield differentials between South Africa and the US. A 0.3% drop in expected CPI automatically widens this gap, potentially attracting inflows if the US MOVE volatility index remains low. However, a global scramble for dollars, indicated by a ballooning one-year dollar-rand cross-currency basis swap, can quickly cause these carry hunters to withdraw. While the rand might benefit from disinflation news, its strength is conditional and vulnerable to shifts in New York funding markets, as evidenced by currency options showing long-term dollar-call bias despite short-term rand favor."},
{"question": "How does lower inflation specifically benefit different income groups within South African households?", "answer": "Lower inflation benefits different income groups within South African households in distinct ways. The poorest fifth of society, who allocate a significant portion (34%) of their budget to food and non-alcoholic drinks, directly benefit from cheaper food prices. A CPI drop from 6% to 4% could provide them with an additional R120 per month on a R3,000 budget. For the middle quintile, whose primary concern is debt service (mortgages, vehicle loans), a potential repo rate reduction stemming from lower inflation is more impactful. A quarter-point cut could save them R166 monthly on a R1 million, 20-year bond. Rural consumers have also shown an increase in confidence due to cheaper goods, although this hasn't yet translated into a significant increase in durable goods purchases, highlighting the need for broader economic improvements beyond just price stability."},
{"question": "What are the varying impacts of lower inflation on major South African corporations like Eskom and mining houses?", "answer": "Lower inflation presents varying impacts on major South African corporations. For Eskom, it can result in a real revenue windfall. If electricity tariffs were calculated based on a higher CPI assumption (e.g., 5%) but actual inflation is lower (e.g., 4.2%), Eskom effectively 'pockets' the difference, providing breathing room for its debt. Conversely, mining houses benefit from lower inflation through reduced wage demands. The Minerals Council estimates that every percentage point shaved from inflation expectations trims central-bargaining wage demands by 0.6%. This can lead to substantial savings, allowing companies to divert funds to other investments like solar energy solutions, as seen with a mid-sized platinum outfit potentially saving R1.1 billion annually."},
{"question": "How does a credible disinflation path influence the banking sector and overall credit growth in South Africa?", "answer": "A credible disinflation path significantly influences the banking sector and overall credit growth in South Africa. Commercial banks, often constrained by regulations like Basel IV, tend to keep credit growth subdued. However, lower inflation sweetens corporate debt-service-coverage ratios, making businesses appear less risky to lenders. This encourages banks to release general provisions and extend more credit. Studies by the South African Reserve Bank (SARB) indicate that credit growth can accelerate by 1.3% for every 1% drop in expected inflation within four quarters. This influx of credit acts as 'rocket fuel' for the economy, which has often operated below its potential. The banking index itself surged by 11% after the forecast change, pricing in not just potential interest rate cuts but also the broader positive narrative of lower defaults, cheaper goods, and increased economic activity."}]
Oliver Daniels is a Cape Town journalist who chronicles the intersection of food, migration and identity in South Africa's kitchens—from wood-fired Gugulethu braai spots to Constantia vineyards. Born and raised on the slopes of Devil’s Peak, he still starts each week with a dawn walk across Table Mountain to catch the first Atlantic light before filing copy.
View all articles →