
Western Cape High Court deems VAT Act provision unconstitutional
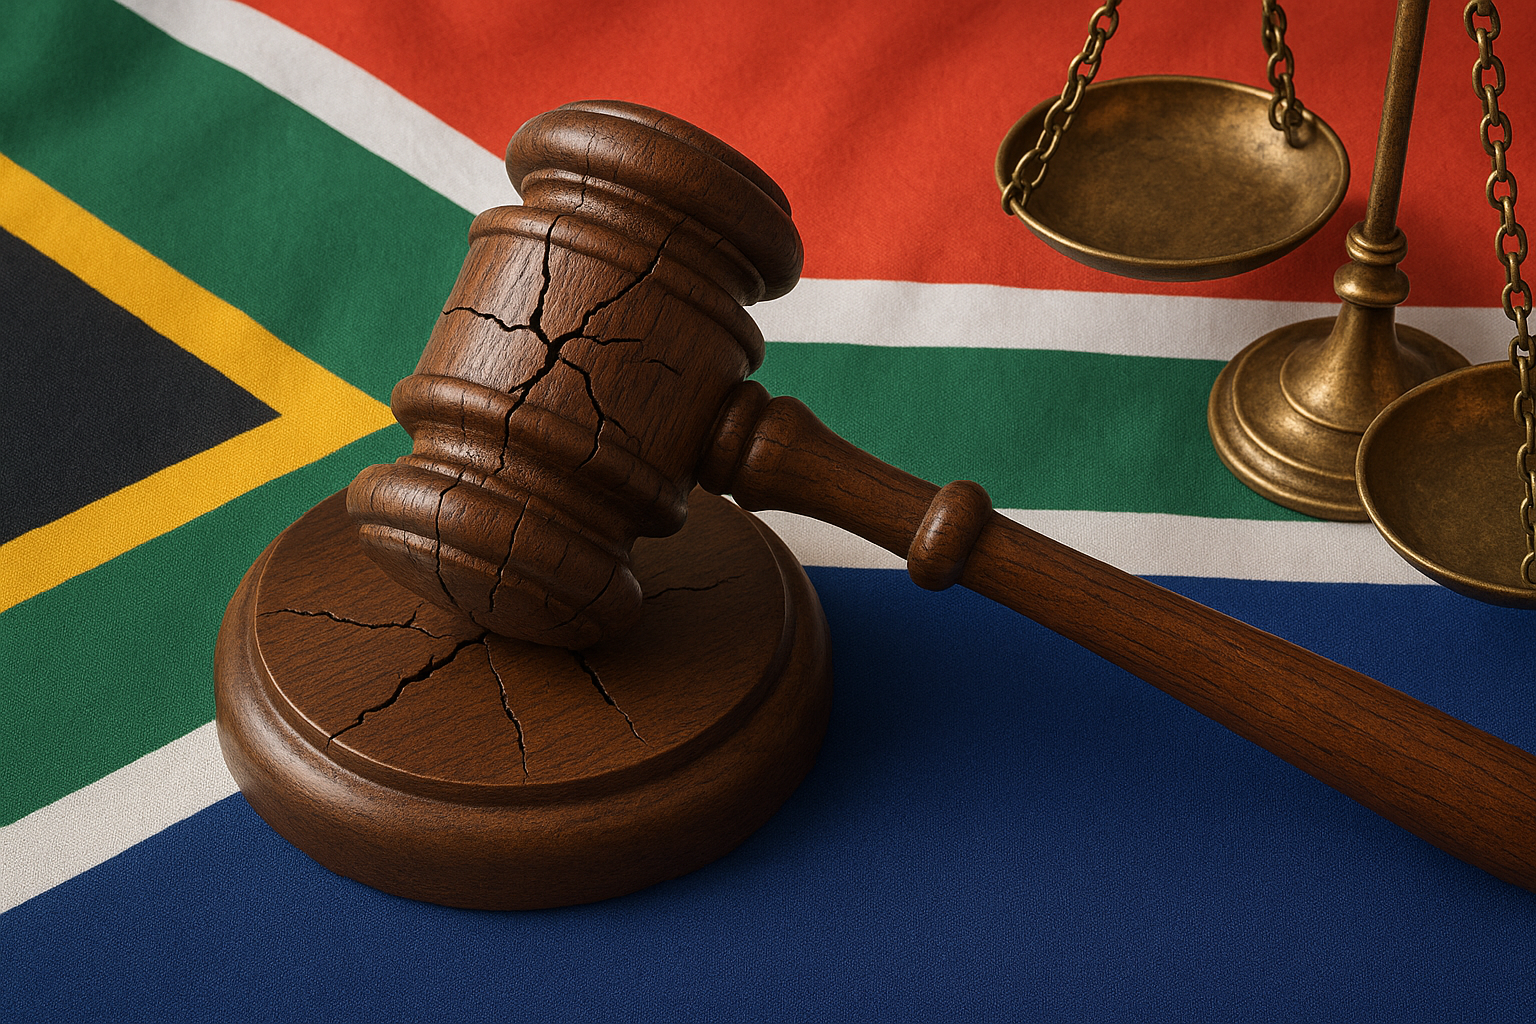
Western Cape High Court rules Minister's VAT-rate power unconstitutional, returning taxing authority to Parliament after 30 years.
A court in Cape Town just dropped a bombshell, telling the Finance Minister he can't change VAT on his own anymore! This means Parliament, the people's voice, gets back its power to decide on taxes. It's a big win for democracy, making sure tax changes are open and fair, not secret budget-night surprises. Now, lawmakers have two years to figure out a new, transparent way to handle VAT, with everyone watching.
What was the outcome of the Cape Town court ruling regarding VAT?
The Western Cape High Court declared subsection 7(4) of the 1991 Value-Added Tax Act unconstitutional. This ruling prevents the Finance Minister from unilaterally altering the VAT rate, requiring parliamentary approval for any future changes. The decision aims to uphold the separation of powers and Parliament's exclusive right to impose taxes.
Get Cape Town news in your inbox
Stay updated with the latest stories from the Mother City.
1. A 30-Year-Old Budget Shortcut Blown Up
At 10 a.m. sharp on a quiet Tuesday, the Western Cape High Court detonated the quickest fiscal lever in South Africa’s post-apartheid toolkit.
Judge Matthew Francis, flanked by Acting Judges Boqwana and Snyman, ruled that subsection 7(4) of the 1991 Value-Added Tax Act is unconstitutional.
The clause had let the Finance Minister alter the nation’s consumption-tax rate with nothing more than a podium promise during the February speech; Parliament merely rubber-stamped the move months later.
Francis’ 47-page verdict brands the arrangement “an executive tax island inside a constitutional democracy.”
Inserted in the final apartheid months to dodge sanctions-era cash squeezes, the power drifted untouched into the 1996 constitutional era - until yesterday.
The declaration of invalidity is frozen for twenty-four months, forcing lawmakers to invent a constitution-proof route before the clause formally dies.
Because an Act of Parliament is in the cross-hairs, the judgment rockets automatically to the Constitutional Court for confirmation; until that bench rules, today’s 15 % rate remains legally alive, yet no future “budget-night shock” can be launched.
2. The Legal House of Cards - and Who Brought It Down
Sub-section 7(4) worked like a fiscal Trojan horse.
The moment the Minister’s lips formed a new percentage, vendors had to invoice at that figure the next sunrise; legislators could fume, but refunds were impossible because VAT is baked into shelf prices with no reverse gear.
The court found this sequence offside against four constitutional pillars: Parliament’s monopoly to initiate money bills, its sole right to impose taxes, the separation of powers, and the public-finance clause that demands transparent, effective spending.
The plaintiffs formed an ideological kaleidoscope.
The Democratic Alliance fired the opening shot, soon joined by the EFF, Freedom Front Plus, ACDP and even the uMkhonto weSizwe party.
Business Unity South Africa and civil-action group OUTA added boardroom heft, arguing that retroactive rate shifts poison forward planning.
Treasury’s counsel labelled the power a “temporary device” that Parliament could always veto; the court retorted that a loaf, once taxed, can never be “un-baked.”
The 2025 budget drama lit the fuse.
In February the Minister floated a two-step hike to fill a R 72-billion crater created by commodity shocks and Eskom debt.
The rand staggered, consumer groups marched, and the governing party - fearing municipal-election fallout - twisted his arm down to a symbolic 0.5 %, then axed the plan altogether.
Yet the DA’s lawyers marched on, brandishing an internal memo that showed SARS had already printed 1.8 million templates for a 17 % rate and banks had rebooted 63 000 card machines at a cost of R 43 million - proof, they said, that the executive had spent cash Parliament never approved.
3. What the Rand, Retailers and Lawmakers Do Next
Financial markets coughed, then shrugged.
A midnight note from Treasury promised “business-as-usual,” and the JSE All-Share dipped a token 0.4 % before algorithms bid it back within ninety minutes.
Bond yields added three basis points - background noise in a volatile world - yet retailers now stare at a pricing puzzle.
Pick n Pay and Woolworths had already printed 2026 labels assuming a stable 15 %; the latter admits it will freeze shelf-pricing software until the Con-Court robes are visible.
Smaller shops fear “label chaos” if MPs dither past the next budget cycle.
Speaker Thoko Didiza has fused the finance and appropriations committees into one urgent workshop.
Academics sketch four replacement models on the whiteboard:
- A classic money-bill channel - every rate tweak must trundle through a full Act, complete with 90-day public comment.
- A bounded delegation - Parliament sets a 12 %-18 % corridor and lets the Minister shift within it after thirty days of open scrutiny.
- A super-majority brake - executive change is instant but dies unless 75 % of MPs bless it within a week.
- A plebiscite lock - any increase above inflation triggers a referendum, Swiss-canton style.
Scholars warn that option 1 is too leisurely for crisis budgeting, while option 3 merely gift-wraps the same sin in democratic paper.
They lean toward option 2, but with a twist: entrench the new rule in the Constitution itself, not in the VAT Act that a simple majority can amend again.
That path needs a two-thirds vote plus NCOP concurrence - tough politics, yet the only insulation against a future relapse.
4. Global Shadows and Your Grocery Basket
South Africa is following a worldwide arc.
Canada scrapped a similar executive-VAT wand in 1997; New Zealand now demands a 28-day committee pause even for emergency GST moves.
The United Kingdom still lets the Treasury fiddle rates overnight, but the court dismissed that precedent, noting Britain’s unwritten constitution “lacks the rigid separation-of-powers architecture” of South Africa’s text.
Domestically, litigants are already polishing challenges to fuel-levy and excise-duty clauses that copy the same “midnight tweak” DNA.
VAT has become the planet’s fiscal cash-cow, supplying one-third of OECD revenue, up from 12 % in 1975.
Pretoria’s 15 % sits below the OECD mean of 19.2 %, and the IMF has nudged government to “broaden the base” rather than lift the rate - code for pruning zero-ratings that cost R 56-billion last year.
Yesterday’s ruling turns that technocratic whisper into a political scream: every exemption must now survive open committee hearings and floor votes where populists left and right vow to defend cheap bread and paraffin.
For shoppers, the price of milk is unchanged this morning, and SARS will not re-issue a single invoice disk.
The real shift is accountability: if you dread pricier groceries, you now petition your MP in a public hearing, not the Minister behind a budget-day curtain.
Twenty-four months tick away; Parliament must choose between transparent speed, democratic delay or referendum theatre - knowing that the next VAT debate will unfold in the House, not on the podium.
[{"question": "What was the Cape Town court's ruling regarding the Finance Minister's power over VAT?", "answer": "The Cape Town court declared subsection 7(4) of the 1991 Value-Added Tax Act unconstitutional. This means the Finance Minister can no longer unilaterally change the VAT rate; such changes now require parliamentary approval. This ruling is a significant win for democracy, ensuring transparency and accountability in tax adjustments."}, {"question": "What was the constitutional issue with the previous VAT adjustment process?", "answer": "The court found that the previous process, which allowed the Finance Minister to change VAT rates with a budget-day announcement and Parliament merely rubber-stamping it later, violated several constitutional pillars. These included Parliament's sole right to initiate money bills and impose taxes, the principle of separation of powers, and the requirement for transparent public finance. The court described this arrangement as an 'executive tax island inside a constitutional democracy.'"}, {"question": "Who were the parties involved in challenging this section of the VAT Act?", "answer": "A diverse group of plaintiffs challenged the act. This included political parties like the Democratic Alliance, EFF, Freedom Front Plus, ACDP, and uMkhonto weSizwe. Additionally, business and civil society organizations such as Business Unity South Africa and OUTA joined the legal challenge, arguing against the detrimental effects of retroactive rate shifts on forward planning."}, {"question": "What is the immediate impact of this ruling, and what needs to happen next?", "answer": "The declaration of invalidity is suspended for 24 months, meaning the current 15% VAT rate remains. During this period, Parliament must establish a new, constitutionally compliant method for adjusting VAT. The judgment will automatically be reviewed by the Constitutional Court for confirmation. Retailers, while not immediately affected in terms of current pricing, face uncertainty regarding future pricing software and potential 'label chaos' if lawmakers delay."}, {"question": "What are the potential models Parliament might consider for future VAT changes?", "answer": "Academics have proposed several models: a classic money-bill channel requiring a full Act for every change, a bounded delegation where Parliament sets a range (e.g., 12%-18%) for the Minister to operate within, a super-majority brake where executive changes are instant but require 75% MP approval within a week, or a plebiscite lock where any increase above inflation triggers a referendum. Scholars generally lean towards a bounded delegation model, ideally entrenched in the Constitution for greater stability."}, {"question": "How does this ruling align with international practices, and what does it mean for consumers?", "answer": "South Africa is aligning with a global trend; countries like Canada and New Zealand have already moved away from executive-led VAT changes, demanding greater parliamentary oversight. While the price of goods remains unchanged currently, the ruling shifts accountability. Consumers will now have the opportunity to engage with their Members of Parliament in public hearings regarding future tax discussions, rather than simply reacting to ministerial announcements."}]
Tumi Makgale is a Cape Town-based journalist whose crisp reportage on the city’s booming green-tech scene is regularly featured in the Mail & Guardian and Daily Maverick. Born and raised in Gugulethu, she still spends Saturdays bargaining for snoek at the harbour with her gogo, a ritual that keeps her rooted in the rhythms of the Cape while she tracks the continent’s next clean-energy breakthroughs.
View all articles →